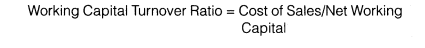Accounting Ratios Question Answers: NCERT Class 12 Accountancy - Company Accounts and Analysis of Financial Statements

Curriculum mapping pending
2 Solutions · 0 Topics · 0 Notes resources

This legacy chapter page is preserved while current curriculum mapping is being verified.

Use this Class 12 Accountancy - Company Accounts and Analysis of Financial Statements chapter hub to study Accounting Ratios from one place. SaralStudy currently provides 2 visible NCERT solution entries on this page.

NCERT Solutions

Review the SaralStudy solution entries currently available for this chapter.

Exercise 1
A:

Ratio analysis is a quantitative procedure of obtaining a look into a firm’s functional efficiency, liquidity, revenues, and profitability by analysing its financial records and statements. Ratio analysis is a very important factor that will help in doing an analysis of the fundamentals of equity.


A:

The various kinds of financial ratios available may be broadly grouped into the following six silos, based on the sets of data they provide:

1)Liquidity Ratios.
2)Solvency Ratios.
3)Profitability Ratios.
4)Efficiency Ratios.
5)Coverage Ratios.
6)Market Prospect Ratios.


A:

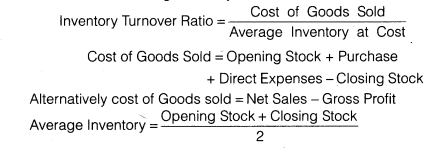
(a) Inventory Turnover Ratio: This ratio is a relationship between the cost of goods sold during a particular period of time and the cost of average inventory during a particular period. It is expressed in number of times. Stock turnover ratio/inventory turnover ratio indicates the number of time the stock has been turned over during the period and evaluates the efficiency with which a firm is able to manage its inventory. This ratio indicates whether investment in stock is within proper limit or not. The ratio is calculated by dividing the cost of goods sold by the amount of average stock at cost. The formula for calculating inventory turnover ratio is as follows
NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios SAQ Q3

(b)Debtor Turnover Ratio :Debtor turnover ratio or accounts receivable turnover ratio indicates the velocity of debt collection of a firm. In simple words it indicates the number of times average debtors (receivable) are turned over during a year. The formula for calculating Debtors turnover ratio is as follows
NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios SAQ Q3.1

(c)Creditors/Payables Turnover Ratio :It compares creditors with the total credit purchases. It signifies the  credit period enjoyed by the firm in paying creditors. Accounts payable include both sundry creditors and bills payable. Same as debtor’s turnover ratio, creditor’s turnover ratio can be calculated in two forms, creditors’ turnover ratio and average payment period. The following formula is used to calculate the creditors Turnover Ratio
NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios SAQ Q3.2

(d)Working Capital Turnover Ratio Working capital turnover ratio indicates the velocity of the utilization of net working capital. This ratio represents the number of times the working capital is turned over in a year and is calculated as follows
NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios SAQ Q3.3


A:

Yes it is true that the liquidity of a business firm is measured by its ability to pay its long term obligations as they become due. Here the long term obligation means payments of principal amount on the due date and payments of interests on the regular basis. For measuring the long term solvency of any business we calculate the following ratios.

Debt Equity Ratio: Debt equity ratio indicates the relationship between the
external equities or outsiders funds and the internal equities or shareholders
funds. It is also known as external internal equity ratio. It is determined to ascertain soundness of the long term financial policies of the company. Following formula is used to calculate debt to equity ratio.

Debt Equity Ratio = External Equities.
                               Shareholders funds

Proprietory Ratio/Total Assets to Debt Ratio: Total assets to Debt Ratio or
Proprietory Ratio are a variant of the debt equity ratio. It is also known as equity
ratio or net worth to total assets ratio. This ratio relates the shareholder’s funds
to total assets. Proprietory / Equity ratio indicates the long-term or future
solvency position of the business. Formula of

Proprietory or Equity Ratio = Shareholders funds
                                             Total Assets

Proprietory/Equity Ratio Interest Coverage Ratio: This ratio deals only with
servicing of return on loan as interest. This ratio depicts the relationship between
amount of profit utilise for paying interest and amount of interest payable. A high
Interest Coverage Ratio implies that the company can easily meet all its interest
obligations out of its profit.

Interest Coverage Ratio = Net Profit before interest and tax
                                          Interest on Long Term loans


A:

Inventory Turnover Ratio: This ratio is a relationship between the cost of goods sold during a particular period of time and the cost of average inventory during a particular period. It is expressed in number of times. Stock turnover ratio/inventory turnover ratio indicates the number of time the stock has been turned over during the period and evaluates the efficiency with which a firm isable to manage its inventory. The formula for calculating inventory turnover ratio is as follows:

Inventory Turnover Ratio = Cost of goods sold
                                           Average Inventory at Cost

Cost of goods sold = Opening Stock + Purchase + Direct Expenses - Closing                                                                                                                          Stock
Alternatively cost of goods sold = Net Sales - Gross Profit
Average Inventory = Opening Stock + Closing Stock
                                                            2

From the above formula, it is clear that this ratio reveals the average length of
time for which the inventory is held by the firm.


Exercise 2
A:

Liquidity ratios are calculated to determine the short-term solvency of a business, i.e. the ability of the business to pay back its current dues. Liquidity means easy conversion of assets into cash without any significant loss and delay. Short-term creditors are interested in ascertaining liquidity ratios for timely payment of their debts.

Liquidity ratio includes:

Current Ratio: It explains the relationship between current assets and current
liabilities. It is calculated as:

Current Ratio = Current Assets/Current Liabilities

Liquid Ratio or Quick Ratio: It explains the relationship between liquid assets and current liabilities. It indicates whether a firm has sufficient funds to pay its current liabilities immediately. It is calculated as:

Liquid Ratio = Liquid Asset/Current LiabilitiesLiquid

Liquids Assets = Current Assets – Stock – Prepaid Expenses.


A:

The solvency position of any firm is determined and measured with the help
of solvency ratios. In this way we can say that the ratios which throw light on the
debt servicing ability of the businesses in the long run are known as solvency
ratios. Solvency of a concern can be measured in two ways first to check the
security of Debt and second is to check the security of return on Debt. For
calculating the security of debt we calculate Debt-Equity Ratio, Proprietory Ratio,
Fixed Assets – Proprietory Fund Ratio, etc. And for calculating Security of Return on Debt we calculate Interest Coverage Ratio.

A brief description of the above mentioned ratios is as follows Debt Equity
Ratio :

Debt Equity Ratio: indicates the relationship between the external equities or
outsiders funds and the internal equities or shareholders funds. It is also known as external internal equity ratio. It is determined to ascertain soundness of the long term financial policies of the company.

Debt Equity Ratio = External Equities
                              Shareholders Funds

Proprietory Ratio/ Total Assets to Debt Ratio: Total assets to Debt Ratio or
Proprietory Ratio are a variant of the debt equity ratio. It is also known as equity
ratio or net worth to total assets ratio. This ratio relates the shareholder’s funds
to total assets. Proprietory/Equity Ratio indicates the long-term or future solvency position of the business. Formula of Proprietary/Equity Ratio

Proprietory or Equity Ratio = Shareholders Funds
                                                   Total Assets

Shareholder’s funds include equity share capital plus all reserves and surpluses
items. Total assets include all assets, including Goodwill. Some authors exclude
goodwill from total assets. In that case the total shareholder’s funds are to bedivided by total tangible assets. The total liabilities may also be used as the
denominator in the above formula.

Fixed Assets to Proprietor’s Fund Ratio: Fixed Assets to Proprietor’s Fund Ratio
establish a relationship between fixed assets and shareholders’ funds. The
purpose of this ratio is to indicate the percentage of the owner’s funds invested fixed assets. The formula for calculating this ratio is as follows The fixed assets are considered at their book value and the proprietor’s funds consist of the same
items as internal equities in the case of debt equity ratio.

Fixed Assets to Proprietors Fund = Fixed Assets
                                                    Proprietors Fund

Interest Coverage Ratio :This ratio deals only with servicing of return on loan as
interest. This ratio depicts the relationship between amount of profit utilise for
paying interest and amount of interest payable. A high Interest Coverage Ratio
implies that the company can easily meet all its interest obligations out of its
profit.

Interest Coverage Ratio = Net Profit before Interest and Tax
                                          Interest on Long Term Loans

A:

Profitability Ratios Profitability ratios measure the results of business operations or overall performance and effectiveness of the firm. Some of the most Important and popular profitability ratios are as under
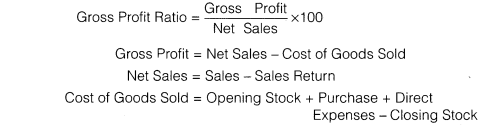
Gross Profit Ratio: Gross Profit Ratio (GP ratio) is the ratio of gross profit to net sales expressed as a percentage. It expresses the relationship between gross profit and sales. The basic components for the calculation of gross profit ratio are gross profit and net sales. Net sales mean sales minus sales returns.

Gross profit would be the difference between net sales and cost of goods sold. Cost of goods sold in the case of a trading concern would be equal to opening stock plus purchase, minus closing stock plus all direct expenses relating to purchases. In the case of manufacturing concern, it would be equal to the sum of the cost of raw materials, wages, direct expenses and all manufacturing expenses. In other words, generally the expenses charged to profit and loss account or operating expenses are excluded from the calculation of cost of goods sold.
Following formula is used to calculate gross profit ratios
NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios LAQ Q4

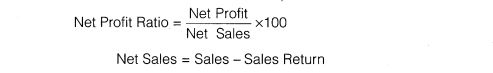
Net Profit Ratio :Net Profit Ratio is the ratio of net profit to net sales. It is expressed as percentage. The two basic components of the net profit ratio are the net profit and sales. The net profits are obtained after deducting income-tax and, generally, non-operating expenses and incomes are excluded from the net profits for calculating this ratio. Thus, incomes such as interest on investments outside the business, profit on sales of fixed assets and losses on sales of fixed assets, etc are excluded.
NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios LAQ Q4.1

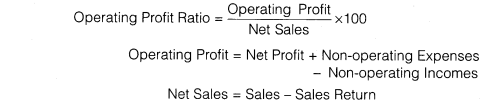
Operating Profit Ratio :Operating Profit Ratio is the ratio of operating profit to net sales. There are many non operating expenses and incomes included in the profit and loss account which has nothing to do with the operations of the business such as loss by fire, loss by theft etc. On the other had in credit side of the P&L account, there are so many incomes
which can be considered as operating incomes such as dividend, bank interest, rent etc. In this way net profit ratio will not tell the truth about the profit of the organisation. Hence operating profit ratio will be helpful in that case. The formula for calculating operating ratio is as follows
NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios LAQ Q4.2

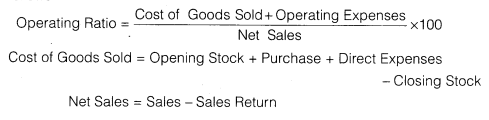
Operating Ratio :Operating ratio is the ratio of cost of goods sold plus operating expenses to net sales. It is generally expressed in percentage, Operating ratio measures the cost of operations per dollar of sales. This is closely related to the ratio of operating profit to net sales. The two basic components for the calculation of operating ratio are operating cost (cost of goods sold plus operating expenses) and net sales. Operating expenses normally include (a) administrative and office expenses and (b) selling and distribution expenses. The formula for calculating the operating ratio is as follows

NCERT Solutions for Class 12 Accountancy Part II Chapter 5 Accounting Ratios LAQ Q4.3


A:

The above mentioned statement is true. There are two different ways to measure the liquidity of a firm first through current ratio of the firm and second through quick ratio of the firm. The second one is considered the more refine form of measuring the liquidity of the firm. The current ratio ‘explains the relationship between current assets and current liabilities. If current assets are quite capable to pay the current liability the liquidity of the concerned firm will be considered good. But here generally one question arises there are certain assets which cannot be converted into cash quickly such as stock and prepaid expenses. As far as the matter of prepaid expenses is concerned it’s ok but what about the stock if we measure the liquidity on the basis of conversion of current assets in cash there are many firms where conversion of stock is not possible into cash frequently say e.g., heavy machinery manufacturing companies, locomotive companies, etc. This is because, the heavy stocks like machinery, heavy tools etc. cannot be easily sold off. In this case it is always advisable to follow the current ratio for measuring the liquidity of a firm. But on the other hand, in case of those firms where the stock can be easily realised or sold off consideration of stock should be avoided and to measure the liquidity of that firm Quick ratio should be calculated, e.g., the inventories of a service sector company are very liquid as there are no stocks kept for sale, so in that case liquid ratio must be followed for measuring the liquidity of the firm. We can understand from the above mentioned statement in the light of another example where stock contribute the major portion in current assets in that case to find out the liquidity of that firm stock cannot be avoided to measure the liquidity of the firm. On the other hand where stock contributes a reasonably less amount it can be avoided and liquidity of that firm can be measured with the help of quick ratio. On the other hand where there is a lot of fluctuation in the price of stock it is always advisable to compute quick ratio and avoid the stock figure because it will reduce the authenticity of liquidity measure.


NCERT Textbook PDF

Use the available NCERT textbook PDF alongside the chapter solutions.

Frequently Asked Questions about Accounting Ratios - Class 12 Accountancy - Company Accounts and Analysis of Financial Statements

    • 1. Is Accounting Ratios in the current curriculum?
    • This legacy chapter page is preserved while current curriculum mapping is being verified.
    • 2. How many NCERT solution entries are currently available for Accounting Ratios?
    • SaralStudy currently shows 2 visible solution entries on this chapter page.
    • 3. Are topic mappings available for Accounting Ratios?
    • No public topic mappings are currently available for this chapter.
    • 4. Are revision notes available for Accounting Ratios?
    • No verified chapter notes are currently available in this hub.

Latest Blog Posts

Stay updated with our latest educational content and study tips

How to Return to Work After a Career Break: Skills, Jobs and Preparation in 2026

It’s not about starting over if you took a break to care for children, take care of yourself, be healthy or for any other reason. This is a realistic strategy for the recovery of skills, selection of the right job, and overcoming the resume problem. One year, three years or 10 years of a career … Read more

Read More

Best Career Options After Class 12 for Average Students in 2026

There’s no need to score 95% or achieve a JEE/NEET rank. You don’t need to score 95% or rank in JEE/NEET to build a solid career. A candid and pragmatic guide to the routes that actually work for students who have an average mark and what to do when faced with the options. ​ If … Read more

Read More

Coaching vs Self-Study: Which is Best in 2026 for Competitive Exams?

AI tools, online platforms that are much cheaper than coaching centres and the changing idea of what “structure” even means have upended this argument more in the past two years than in the decade preceding it. Here’s what is really the case for 2026 – and what has actually stayed the same. If you look … Read more

Read More

Career Change After 30: How to Transition from Non-Tech to IT or Data Science

Starting to make a new career after 30 isn’t a start from scratch. Marketing, teaching, financial, retail, healthcare, sales and other professionals can pursue careers in technology by applying the existing knowledge and skills they have acquired to new technology skills. There are various ways to enter the technology industry, such as in IT support, … Read more

Read More

Benefits of Using Our NCERT Solutions for Class 12 Accountancy - Company Accounts and Analysis of Financial Statements

When it comes to excelling in your studies, having a well-structured study guide can make a huge difference. Our NCERT Solutions for Class 12 Accountancy - Company Accounts and Analysis of Financial Statements provide you with a comprehensive, easy-to-understand, and exam-focused resource that is specifically tailored to help you maximize your potential. Here are some of the key benefits of using our NCERT solutions for effective learning and high scores:

NCERT Solutions for Effective Exam Preparation

Preparing for exams requires more than just reading through textbooks. It demands a structured approach to understanding concepts, solving problems, and revising thoroughly. Here’s how our NCERT solutions can enhance your exam preparation:

  • Clear Understanding of Concepts: Our NCERT solutions are designed to break down complex topics into simple, understandable language, making it easier for students to grasp essential concepts in Accountancy - Company Accounts and Analysis of Financial Statements. This helps in building a solid foundation for each chapter, which is crucial for scoring high marks.
  • Step-by-Step Solutions: Each solution is presented in a detailed, step-by-step manner. This approach not only helps you understand how to reach the answer but also equips you with the right techniques to tackle similar questions in exams.
  • Access to Important Questions: We provide a curated list of important questions and commonly asked questions in exams. By practicing these questions, you can familiarize yourself with the types of problems that are likely to appear in the exams and gain confidence in answering them.
  • Quick Revision Tool: Our NCERT solutions serve as an excellent tool for last-minute revision. The solutions cover all key points, definitions, and explanations, ensuring that you have everything you need to quickly review before exams.

Importance of Structured Answers for Scoring Higher Marks

In exams, it's not just about getting the right answer—it's also about presenting it in a well-structured and logical way. Our NCERT solutions for Class 12 Accountancy - Company Accounts and Analysis of Financial Statements are designed to guide you on how to write answers that are organized and effective for scoring high marks.

  • Precise and Concise Answers: Our solutions are crafted to provide answers that are to the point, without unnecessary elaboration. This ensures that you don't waste time during exams and focus on delivering accurate answers that examiners appreciate.
  • Step-Wise Marks Distribution: We understand that exams often allot marks based on specific steps or points. Our NCERT solutions break down each answer into structured steps to ensure you cover all essential points required for full marks.
  • Improved Presentation Skills: By following the format of our NCERT solutions, you learn how to present your answers in a systematic and logical manner. This helps in making your answers easy to read and allows the examiner to quickly identify key points, resulting in better scores.
  • Alignment with NCERT Guidelines: Since exams are often set in alignment with NCERT guidelines, our solutions are tailored to follow the exact format and language that is expected in exams. This can improve your chances of scoring higher by meeting the examiner's expectations.
Keep learning

Discover More on SaralStudy

Explore all articles